Introduction: Rethinking What a Personal Loan Can Do for You
Most people think of a personal loan as a last resort — something you take out when you’re short on cash or facing an emergency. That mindset costs borrowers money and opportunity every year.
Used correctly, a personal loan is a financial tool, not a financial burden. It can consolidate high-interest debt, build your credit profile, fund income-generating decisions, and give you predictable, fixed payments in a world of variable-rate uncertainty. The difference between a personal loan that drains your finances and one that strengthens them almost never comes down to the loan itself — it comes down to how it’s structured, used, and repaid.
According to the Federal Reserve’s most recent Survey of Consumer Finances, unsecured personal loan balances have grown steadily as more Americans use them to replace higher-cost credit card debt. That’s not a coincidence. With average credit card APRs sitting well above 20% and personal loan rates for qualified borrowers often landing 8–10 points lower, the math frequently favors a personal loan — if you know how to use it.
This guide walks through exactly how to do that: the strategies that turn a personal loan into an asset, the risks that turn it into a liability, and a practical calculator you can use to model your own numbers before you sign anything.
What Makes a Personal Loan Different From Other Credit Products
Before diving into strategy, it’s worth understanding the mechanics that make personal loans unique in the US lending landscape:
- Fixed rates and fixed terms. Unlike credit cards, most personal loans come with a fixed interest rate and a set repayment schedule — typically 24 to 84 months. You know exactly what you owe and when you’ll be debt-free.
- Unsecured, in most cases. The majority of personal loans don’t require collateral, which means your home or car isn’t on the line — though it also means lenders price in more risk through the interest rate.
- Regulated disclosure requirements. Under the Truth in Lending Act (TILA), lenders are required to disclose the Annual Percentage Rate (APR), total finance charges, and payment schedule before you sign. Reading this disclosure carefully is one of the simplest ways to protect yourself.
- Reporting to credit bureaus. Personal loans are installment credit, which is a different credit mix category than revolving credit (credit cards). Adding installment credit to a file that’s mostly revolving debt can, over time, improve your credit mix score component.
Strategy 1: Use It to Consolidate High-Interest Debt
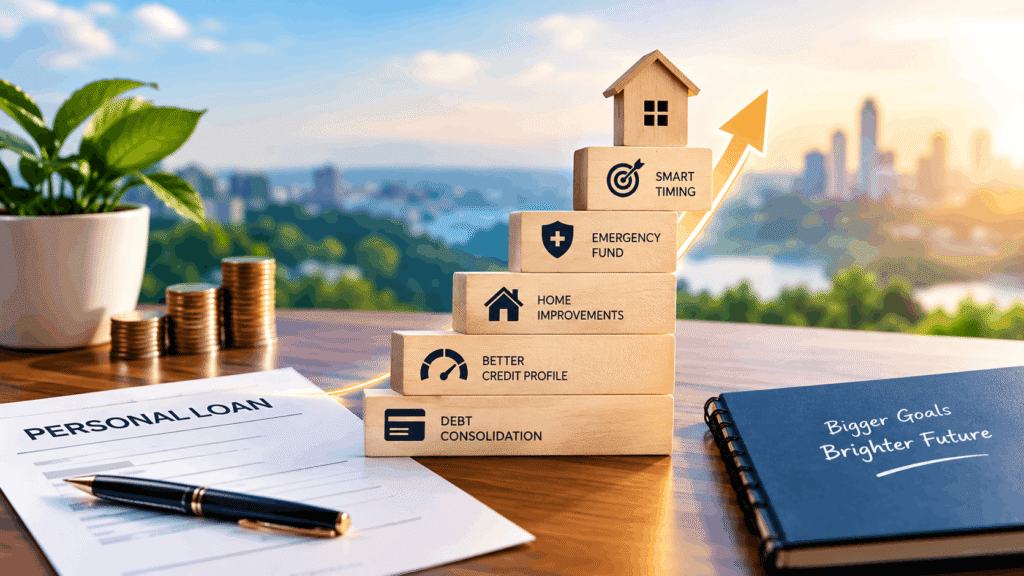
This is the single most common way a personal loan becomes an asset rather than a liability.
If you’re carrying balances across several credit cards at 22–28% APR, a personal loan at a lower fixed rate can:
- Reduce your total monthly interest cost
- Simplify multiple payments into one
- Create a firm payoff date, which credit cards don’t offer
The key mistake to avoid: consolidating credit card debt with a personal loan and then running the credit cards back up. The loan only becomes an asset if you close the gap between what you owe and what you spend — not just move the debt around.
Strategy 2: Build a Stronger, More Diverse Credit Profile
Credit scoring models, including FICO and VantageScore, weigh “credit mix” as a factor. A borrower with only credit cards often scores lower on this metric than one with a healthy mix of revolving and installment credit.
A personal loan, paid on time every month, demonstrates to future lenders — mortgage underwriters included — that you can manage a structured repayment obligation. This matters most for borrowers who are 12–24 months out from applying for a mortgage or auto loan and want to strengthen their file in advance.
Strategy 3: Fund Value-Adding Home Improvements
Unlike a discretionary purchase, certain home improvements — energy-efficient windows, HVAC upgrades, roof repair — protect or increase the value of what is, for most Americans, their largest asset. A fixed-rate personal loan avoids the variable-rate risk of a HELOC and doesn’t require the home equity that a newer homeowner may not yet have.
Strategy 4: Cover a True Emergency Without Wrecking Your Long-Term Plan
Medical bills, urgent car repairs, and similar shocks are among the top reasons Americans borrow. A personal loan with a fixed, manageable monthly payment is frequently a better option than high-APR credit card debt or, worse, a payday loan — which the Consumer Financial Protection Bureau (CFPB) has flagged repeatedly for its cycle of repeat borrowing.
Strategy 5: Time It Around Your Credit Profile, Not the Market
Personal loan rates are driven heavily by your credit score, debt-to-income ratio, and the lender’s own underwriting model — not by trying to “time” the market the way you might with a mortgage refinance. The most effective move a borrower can make isn’t waiting for rates to drop; it’s spending 60–90 days paying down revolving balances and correcting any credit report errors before applying, since that has a far larger effect on the rate you’re offered.
The Real Risks — and How to Mitigate Them
A personal loan isn’t automatically a good decision. Here’s where it goes wrong, and how to protect yourself.
Risk: Using it to fund lifestyle spending. A personal loan for a vacation, wedding, or discretionary purchase adds a fixed debt obligation without adding any offsetting value or return. Mitigation: reserve personal loans for debt consolidation, necessary repairs, or clearly value-adding purposes — not discretionary spending you can’t otherwise afford.
Risk: Origination fees eating into the benefit. Many personal loans carry an origination fee of 1–8% of the loan amount, deducted before you receive funds. Mitigation: always compare the APR (which includes fees), not just the headline interest rate, when evaluating offers.
Risk: Prepayment penalties. Some lenders charge a fee for paying off the loan early, which can undercut a debt-payoff strategy. Mitigation: confirm there’s no prepayment penalty before signing — it’s disclosed under TILA, so it should be in your loan documents in plain terms.
Risk: Stacking loans. Taking out a second personal loan to cover payments on the first is a warning sign of a debt spiral, not a strategy. Mitigation: if you find yourself considering this, that’s the moment to talk to a nonprofit credit counselor (many are accredited through the National Foundation for Credit Counseling) rather than a new lender.
Risk: Damaging your credit through missed payments. Because personal loans report to all three major credit bureaus, a missed payment can do real damage to your score. Mitigation: set up autopay for at least the minimum payment, and build the payment into your budget before you accept the loan, not after.
How to Decide If a Personal Loan Is Right for You
Ask yourself three questions before applying:
- Does this loan replace a more expensive form of debt, or add a new obligation on top of what I already have?
- Can I comfortably absorb this monthly payment if my income dipped by 10–15% next year?
- Is there a clear, calculable benefit — lower total interest, a firmer payoff date, a protected or improved asset — or am I borrowing simply because the money is available?
If your answers point toward consolidation, credit building, or protecting an asset you already own, a personal loan is very likely working in your favor. If they point toward discretionary spending or covering a shortfall you don’t have a plan to close, it’s worth pausing.
Conclusion: The Asset Is in the Strategy, Not the Loan Itself
A personal loan doesn’t become a financial asset because of its interest rate, its lender, or its marketing. It becomes an asset because of the plan behind it — a clear purpose, a realistic repayment budget, and the discipline to avoid turning it into a stopgap for ongoing overspending.
Approached this way, a personal loan is one of the most flexible tools available to US borrowers: fixed payments, no collateral in most cases, and a direct path to paying down more expensive debt or protecting the value of what you already own. The borrowers who come out ahead aren’t the ones who found the lowest rate — they’re the ones who used the loan with a plan.
Before you apply, run your own numbers. The calculator below lets you model your monthly payment, total interest, and full amortization schedule so you can see exactly what you’re signing up for.
Personal Loan Repayment Calculator
Estimate your monthly payment, total interest, and full payoff schedule.
This calculator provides estimates for informational purposes only and does not constitute financial advice. Actual loan terms depend on your lender and creditworthiness.