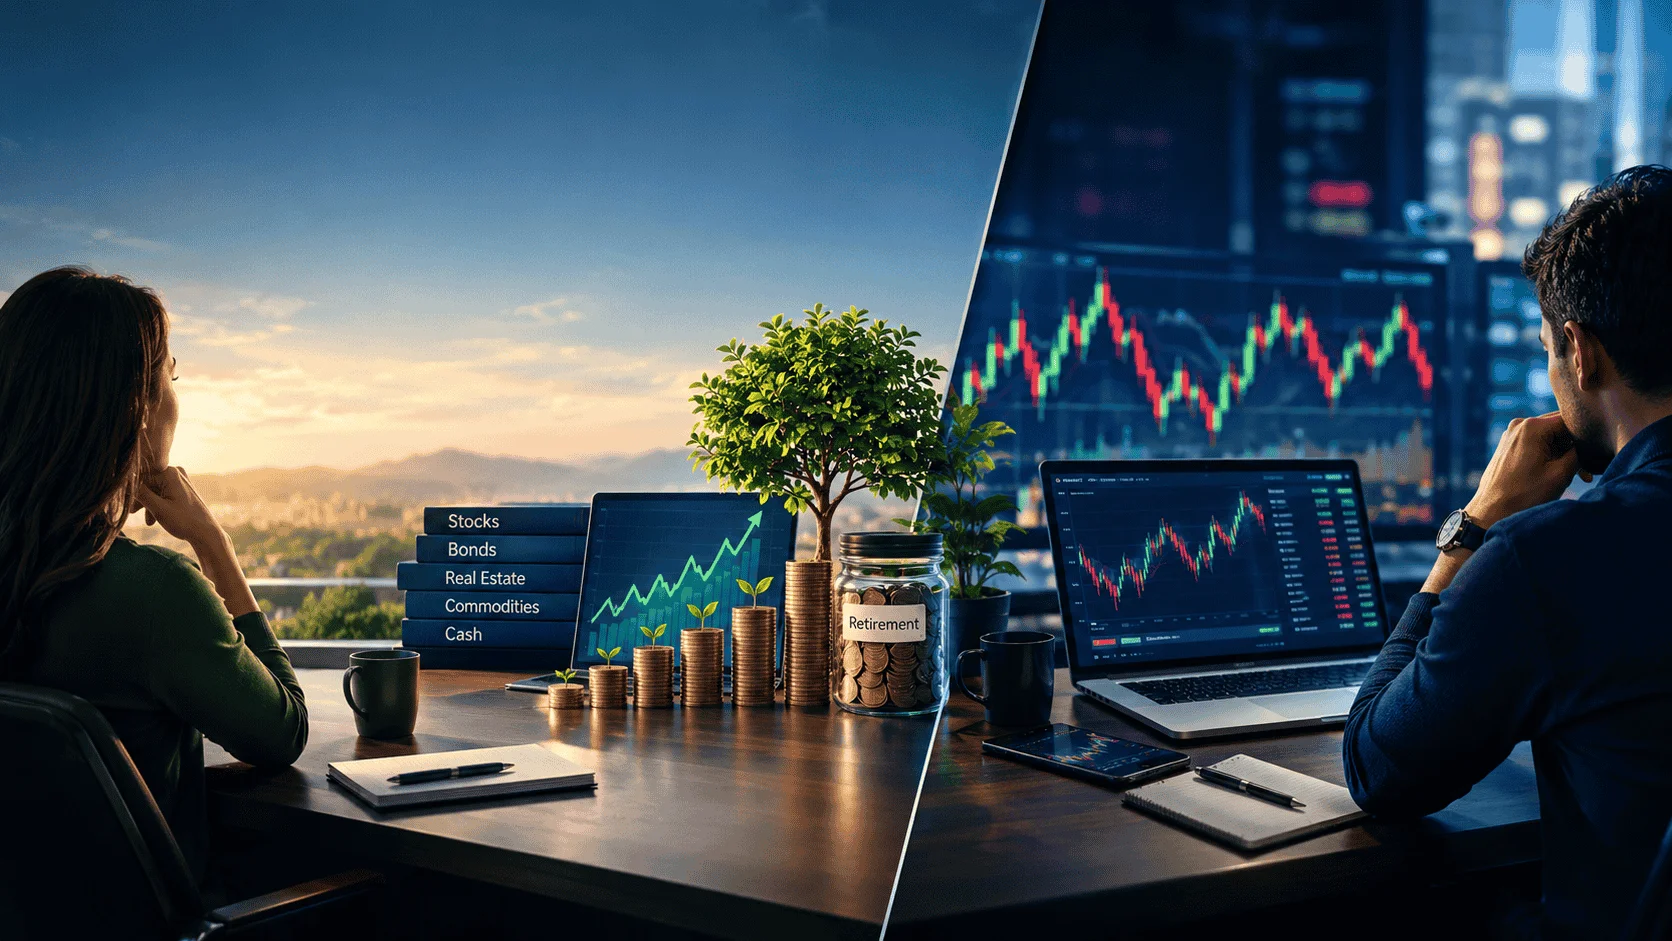
Creating wealth through investment is more than selecting a stock or a fund. Your time horizon can be as significant as it can get. Some investors prefer to invest for long periods of time. Others attempt to benefit from changes in value that occur over a period of months, weeks or even days.
This makes the topic of Long-Term vs Short-Term Investing one to consider when putting together a financial plan.
For the majority, the primary concern isn’t how fast an investment can make money; instead, it’s how to save enough to invest for a goal like retirement. It is a measure of how well the strategy aligns with the objective, risk, time horizon, and investor’s capacity to remain invested.
What is long term investing?
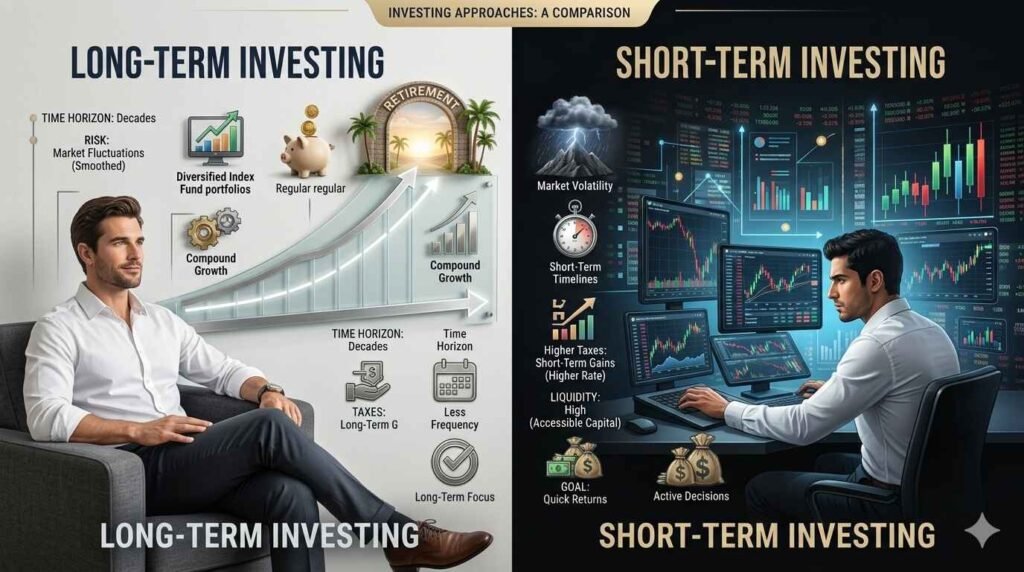
Long-term investing involves purchasing investments for the long-term, typically over a period of several years or more. Americans often take a long-term strategy with their retirement accounts, like a 401(k) or an IRA.
A long-term investor might purchase diversified stock funds, ETFs, mutual funds, bonds or other investments and keep them over varying market conditions.
The key principle is to let your investments grow.
As pointed out by the SEC, compound growth can be even more potent if it is not removed from the market for extended periods. You can get the return of your investment and maybe the return of the previous investment as well.
Also, long-term investing provides investors with more time to experience some temporary declines in the market. It does not take away the risk associated with investing. Stocks can drop drastically and some investments can actually become worthless. But when the market is volatile, a longer time frame provides an investor with greater flexibility.
Short Term Investing Definition
Short-term investing is a strategy that focuses on the short-term with the goal of taking advantage of relatively quick price changes.
Time period may be anywhere between. This can mean that the stock is held for months, weeks or even days. In general, the short-term trading is more active than the traditional long-term investing.
This method calls for investors to make decisions more often. Prices can be affected by market news, economic reports, company announcements, interest rates, and investor sentiment.
The SEC cautions that trading on a short-term time frame in volatile markets may present serious risk of loss. It also cautions that emotional investing, reacting to market swings or social media, can be detrimental to investors.
But not all short-term investments are guaranteed to be profitable. It implies that the hazards and requirements are distinct from a long-term strategy.
Long-Term vs Short-Term Investing: Key Differences
The biggest difference is the amount of time you plan to keep your money invested.
| Factor | Long-Term Investing | Short-Term Investing |
| Typical horizon | Several years or more | Months, weeks, or days |
| Main goal | Long-term wealth building | Short-term price opportunities |
| Trading activity | Usually lower | Usually higher |
| Market volatility | More time to absorb fluctuations | Can have a larger immediate impact |
| Research needs | Ongoing but less frequent | Often more frequent |
| Tax considerations | Potentially favorable for taxable accounts | Short-term gains can receive less favorable tax treatment |
| Time commitment | Generally lower | Often higher |
| Best suited to | Long-term goals | Specific short-term objectives and experienced strategies |
The right approach depends on the investor’s goal and circumstances.
Concept of time is important when it comes to wealth.
One of the best assets an investor can have is time.
Suppose a person invests $300 each month for a long term investment. The investor is not depending on just the investment capital. Time can create positive returns from investment returns.
The concept behind compounding is the simple idea.
The SEC offers examples of how over a long period of time, regularly investing can lead to significant growth, though returns from investing will differ.
One of the reasons Long-Term vs Short-Term Investing is important when it comes to retirement planning.
Someone saving for retirement at age 25 could have many years left to wait for retirement. A home buyer who is saving for two years is in a vastly different situation than someone who is saving for a trip in two years.
That should be reflected in the investment strategy.
Taxes Can Also Change the Picture.
Another key factor for U.S. investors is taxes.
If an asset you invest in is held in a taxable account, the IRS typically considers capital gains to be short-term when the asset was held for 1 year or less. Long-term capital gains are likely to be gains from assets that have been held for more than a year. In certain circumstances, different taxes may apply.
The difference is important in making a decision about selling an investment.
But investors shouldn’t keep an investment because they feel it may provide a tax advantage for them. The financial goal, risk and overall plan should always precede financial decisions.
Tax laws may also be amended. Current IRS guidance and/or consult a qualified tax professional should be reviewed for each investor’s specific situation in the U.S.
The Importance of Risk and Diversification.
There are risks with both methods.
An investor can end up losing money in the stock market even if they are a long-term investor. A person who is a short-term trader can also earn a profit. Both strategies have no guarantee of the outcome.
The difference is the length of time an investor has to handle the ups and downs of the market.
Understanding the investor’s time horizon and risk tolerance is important when making asset allocation decisions, the SEC explains in the statement. Investors with longer time horizons may be able to withstand volatile investments more than those with shorter time horizons may be able to withstand equally volatile investments.
Another key consideration is diversification.
Diversification distributes funds among various investments, rather than placing all capital in a single investment or company. It does not prevent losses, but it can help to minimize the effects of a single investment on the rest of the portfolio.
What’s the better strategy to retirement?
Retirement is usually a long-term financial goal.
Retirement investing may include a 401(k) plan offered by a place of employment or an IRA, or both, for many Americans. Some of the workplace plans offer employer matching contributions as well.
The SEC encourages investors to consider retirement accounts such as 401(k)s and IRAs as part of a long-term wealth-building plan. It also notes that regularly investing a portion of income can help investors build wealth over time.
A retirement portfolio does not have to remain unchanged forever. As the retirement date approaches, an investor may adjust the mix of stocks, bonds, and other assets based on changing needs and risk tolerance.
The important point is that retirement money usually has a much longer purpose than money needed for a near-term expense.
When Short-Term Investing May Make Sense
Short-term investing can have a role in a larger financial plan, but the goal must be clear.
For example, someone may require funds for a goal that is approaching in the near future. In such instances, protecting funds may be more important than seeking rapid investment development.
This is where the distinction between investing and saving becomes significant.
The SEC cautions that savings accounts are ideal for short-term goals and emergency finances, whereas investments may lose principal.
Someone who needs $10,000 for an upcoming expense may not want to subject that money to the same market risk as retirement savings that will not be required for decades.
Common Mistakes Investors Should Avoid
Whether you choose a long-term or short-term approach, several mistakes can damage your financial progress.
Chasing Fast Returns
Promises of fast and easy investment profits should raise questions. The SEC specifically warns investors about opportunities that promise high returns with little or no risk.
Trading Based on Emotion
A falling market can create fear. A rapidly rising stock can create excitement. Making decisions based only on these emotions can lead to poor timing.
Ignoring Fees
Investment fees may look small, but they can reduce portfolio growth over many years. Investors should understand the fees attached to their accounts and investments.
Failing to Diversify
Putting too much money into one stock, sector, or asset can create unnecessary concentration risk.
Investing Money Needed Soon
Money needed for rent, emergency expenses, tuition, or another near-term obligation should be treated differently from money intended for retirement.
Long-Term vs Short-Term Investing: What Should You Consider?
Instead of asking which strategy is universally better, start with five questions:
1. What is the goal?
Retirement, a home, education, or another goal may require different approaches.
2. When will you need the money?
Your time horizon can influence how much market volatility you can reasonably accept.
3. How much risk can you handle?
Think about both your financial ability and your comfort with losses.
4. Are you investing in a taxable account?
Tax consequences can differ depending on how long you hold an investment.
5. Can you stay disciplined?
A strategy only works if you can follow it through different market conditions.
Final Thoughts
Long-Term vs Short-Term Investing is less about finding a single winning strategy and more about matching your investment approach to your financial goals.
For long-term goals such as retirement, staying invested, contributing consistently, diversifying, and allowing compounding to work overtime can be important parts of a wealth-building plan.
Short-term strategies have different risks and may require more active decisions. They should not be confused with a savings strategy for money that must remain readily available.
For many U.S. investors, the most useful starting point is to identify the goal, establish the time horizon, understand the risks, and then choose investments that fit the overall financial plan.
Wealth building usually does not happen from one perfect investment decision. It is often the result of consistent saving, sensible investing, diversification, controlling costs, and giving your money enough time to work.