Building wealth does not necessarily require high income, a fool-proof investment system or any financial luck. In most cases, it’s simply a matter of performing simple actions repeatedly over an extended period of time .
The main focus of your everyday action is to keep more of what you earn, Minimize spending, and save money for emergency need. Investors.gov writes that your regular deposits don’t have to be huge to build great wealth—so long as you let a long period of time pass so that additional profits yield further earnings.
If you want to understand how to build wealth, focus less on quick wins and more on financial habits you can maintain for years. Here are 8 practical steps that can help you move toward greater financial security.
1. Create a Realistic Budget
A budget gives clear purpose to your money before you spend it. When you don’t have one, little things can chip away at your income – daily restaurant meals, paid subscriptions, countless small purchases or impulsive online orders – over time to take a much bigger chunk than you expect.
The first step is to define what you bring in on a monthly basis, and then write down your regular, non-negotiable monthly obligations such as rent/mortgage, utilities, loan payments and insurance premium payments, along with your variable expenses, such as food and entertainment.
A few simple habits can make your budget easier to maintain:
- Give every dollar a purpose, whether it goes toward bills, savings, debt repayment, or personal spending. This approach is often called a zero-based budget.
- Separate your needs from your wants so you know where you can cut back without making your lifestyle feel unnecessarily restrictive.
- Don’t just write up a budget and stuff it in a drawer; it needs to be reviewed on a monthly basis..
- Adjust your spending categories when your financial priorities change rather than creating a budget once and forgetting about it.
A realistic budget that you review regularly provides the foundation for many of the other wealth-building habits that follow.
2. Pay Yourself First
The “pay yourself first” approach takes the opposite view. You put money toward your financial goals before giving yourself the opportunity to spend it elsewhere.
Basically, you are saving first, and then spending the rest.
You can make this habit much easier by automating your savings. For example, you can set up:
- Automatic transfers from your checking account to savings
- Payroll contributions to a 401(k)
- Direct deposits into separate savings accounts
- Automatic IRA contributions could also be established with your financial institution.
- Dedicated savings goals for emergencies, a home, or retirement
It also helps to give each account a specific purpose. You might have one account for your emergency fund, another for a future home down payment, and another for a planned vacation.
This strategy is even easier if you designate one particular account for a specific savings purpose, such as one for your emergencies, one for your house down payment, etc.
3. Build an Emergency Fund
Unexpected expenses are unavoidable. An auto repair, a medical bill, a broken refrigerator, or a disruption in income may occur if you don’t have cash on hand to pay for such an event.
An emergency fund is used to provide the available funds that cover these incidents. An emergency fund is available for expenses such as:
- Automobile or home repair
- A medical bill
- A break in income
- An unknown bill or a needed replacement appliance
Keep this money somewhere safe and easily accessible, such as an appropriate savings account at a bank or credit union.
Your emergency fund is not primarily there to earn the highest possible investment return. Its main purpose is to give you financial stability and quick access to cash when an unexpected expense occurs.
4. Pay Down High-Interest Debt
High interest debt especially credit card debt is one of the greatest hindrances to building wealth. The only reason for this is because instead of working for you interest can really compound against you
When you make only the minimum payment, a significant portion of that payment may go toward interest rather than reducing the amount you owe. As a result, the debt can remain for years and cost considerably more than the original balance.
There are several ways to approach debt repayment:
- List your debts by interest rate and direct extra payments toward the highest-rate balance first. This is known as the debt avalanche method.
- Alternatively, focus on paying off your smallest balance first. The debt snowball method can provide quick psychological wins and help maintain motivation.
- Try to staying away from picking up any more high-interest debt during that time.
- Consider looking at a lower interest consolidation loan if appropriate.
The money you save from not giving to unnecessary interest can instead be put towards growing your own wealth through savings and investments.
5. Take Advantage of Your 401(k) and IRA
For many Americans, retirement accounts can potentially play a role in a wealth-creation strategy
The 401(k) option enables participating employees to contribute by means of withholding from their paychecks. Contributions to a traditional 401(k) typically made before paying income taxes are placed in the plan, and contributions to a designated Roth 401(k) is made after you’ve paid your income taxes on that contribution. Employers will often make matching contributions.
If your employer offers a matching contribution, take the time to understand the plan’s rules and consider contributing enough to receive the available match. Employer contributions can provide an additional boost to your retirement savings without requiring you to fund the entire amount yourself.
An IRA may also be worth considering:
- A traditional IRA may allow tax-deductible contributions if you qualify, while taxes are generally deferred until you withdraw the money.
- A Roth IRA is funded with after-tax contributions, and qualified withdrawals may be tax-free.
- Eligibility, income limits, tax treatment, contribution limits, and withdrawal rules vary depending on your circumstances.
Neither account is the optimal fit for everyone. Your income, tax bracket, age, employer-sponsored plan, financial goals, and expectations about future taxes can all influence which option makes more sense.
For current information, the IRS guidance on 401(k) plans and Traditional and Roth IRAs can help you understand the applicable rules.
Once you have a strategy in place, automate your contributions whenever possible. You can also consider increasing your contributions gradually as your income grows.
6. Start Investing Consistently
Consistent investing offers one of the strongest answers to the question of how to build wealth. You don’t need to find the perfect time to enter the market and you don’t need to predict accurately which of the stocks will perform the best.
Rather, structure your investment strategy around a handful of important factors:
- Your investment goals
- When you will need the money (your time horizon for investment)
- How many investment losses can you afford to make,
- how much money can you afford to lose,
- Your portfolio mix of different investments
Diversification means spreading your money across different investments rather than relying heavily on a single company, industry, or asset. Diversified mutual funds and exchange-traded funds can provide exposure to a wide range of securities, although they still carry investment risk and can lose value.
Your investment approach should also reflect when you will need the money. Investing money that you may need within a few months is very different from investing for retirement that is decades away. Short-term goals may call for a more conservative approach, while long-term investments generally have more time to withstand market fluctuations.
Try not to make emotional decisions based on daily market fluctuation. A clear long-term strategy, regular contributions, and periodic reviews are generally more useful than constantly trying to predict the market’s next move.
7. Let Compound Growth Work for You
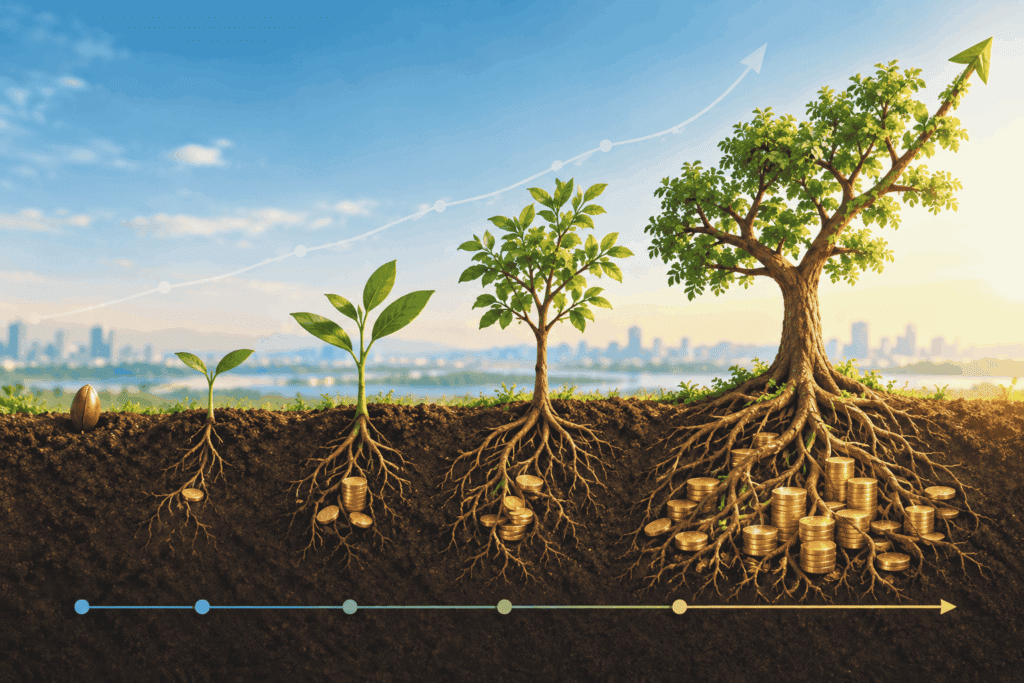
Compound growth occurs when your money earns returns and those returns remain invested so they can potentially earn returns of their own. Over time, this creates a snowball effect.
A simple example: imagine investing $100 each month in a diversified investment and leaving the earnings invested. The money you contribute is the foundation, but over many years, potential growth can begin contributing to future growth. The result depends on the investment’s performance, fees, taxes, and timing, so no specific return is guaranteed.
The basic formula is:
Regular contributions + time + potential investment growth = long-term wealth-building potential
Starting earlier can help because your money has more time to grow. Starting later does not mean you cannot make progress, but you may need larger contributions or a longer working period to reach the same goal.
Use the Investor.gov compound-interest calculator to test different contribution amounts and time horizons. Treat the results as estimates, not promises.
8. Review Your Finances Regularly
You don’t have to worry about money every single day but not checking your finances at all creates problems in your finances.
Set aside 30 minutes once a month for a financial check-in. Review:
- Net worth
- Savings balances
- Debt balances
- Investment contributions
- Monthly spending
- Financial goals
- Unused subscriptions
- Insurance coverage
- Major upcoming expenses
Track how you are progressing over months with no self-judgment. Was monthly spending larger than estimated then figure out the reason why and plan the next month’s budget around what happened in this one.
Regular reviewing your finance system helps it change to what life is like now.
How to Build Wealth Starting From Zero
Starting from zero seems overwhelming, but you do not need a large amount of money to begin. Your first goal should be creating a basic financial Plan.
Start by just monitoring your income and expenses for a month. Pick one or two expenses you can either eliminate or reduce without creating an unrealistic budget and setup a simple automated transfer into an account, no matter how small ($10-$25 per paycheck is enough).
Next, focus on financial stability. Build a starter emergency fund, pay at least the minimum on all debts, and create a plan for high-interest balances. If your employer offers a retirement plan with matching contributions, understand the rules and consider contributing enough to qualify for the available match.
Once your foundation is stronger, increase contributions gradually. You can raise your savings rate when you receive a raise, pay off a loan, reduce an expense, or earn additional income.
There’s no need to wait until you have a sizable amount available to invest. The only “rule” for an early step such as this is the ability to recreate that one act repeatedly. Ultimately larger or more recent dollar amounts are insignificant in the grand scheme of finances against amounts achieved consistently.
Conclusion
Learning how to build wealth is less about finding one perfect financial move and more about repeating smart decisions for a long time. Create a realistic budget, pay yourself first, build emergency savings, reduce high-interest debt, use retirement accounts thoughtfully, and invest consistently according to your goals.
Then protect your progress by controlling lifestyle inflation, reviewing your finances, and increasing your income. Small actions may seem insignificant at first, but consistency gives them the opportunity to compound into greater financial security over time.
Frequently Asked Questions
How much money do I need to start building wealth? There’s no minimum. Many of these habits — budgeting, automating a small transfer, paying yourself first — can start with whatever amount you have available, even if it’s just a few dollars a week.
Is it better to pay off debt or invest first? It depends on the interest rate. High-interest debt, like credit cards, typically costs more than most investments earn, so it usually makes sense to prioritize that first, while still contributing enough to capture any employer 401(k) match.
How long does it typically take to build wealth? There’s no fixed timeline, since it depends on income, expenses, and consistency. What matters most is starting as early as possible and staying consistent, since compound growth rewards time more than it rewards large lump sums.
Do I need a financial advisor to get started? Not necessarily. Many of these habits can be built independently. That said, a financial or tax professional can be valuable for more complex decisions, such as choosing between account types or planning around a specific goal.